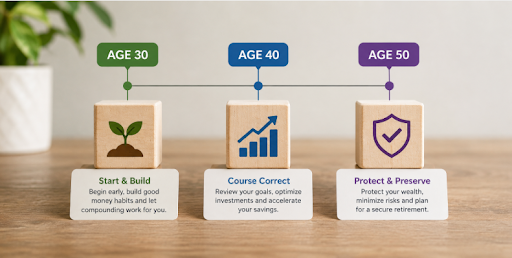
Almost every week, a client asks me the same underlying question, just dressed up differently depending on their age. Someone in their 30s asks me how much they should be saving. Someone in their 40s asks me if they’ve already lost too much time. Someone in their 50s asks me if it’s too late to fix things. The honest answer is that retirement planning looks completely different at each of these stages, and treating it the same way regardless of age is one of the most common mistakes I see.
I’ve spent over two decades as a mutual fund distributor in Mumbai, and if there’s one pattern that holds across almost every client, it’s this: the earlier you tailor your retirement planning to your actual decade of life, the less painful the second half of that journey becomes. Let’s walk through what deserves your attention in your 30s, 40s, and 50s.
In Your 30s: Build the Habit, Let Compounding Do the Heavy Lifting
Your 30s are, without question, the cheapest decade to plan for retirement. Every rupee you invest here has 25 to 30 years to compound, which means even modest, consistent savings can grow into a serious retirement corpus by the time you’re ready to stop working.
The mistake I see most often at this age isn’t a lack of income – it’s a lack of urgency. Many young professionals assume retirement is far enough away that it can wait until their salary “settles down.” But the cost of delaying even by five years is massive, because you lose exactly the years where compounding does most of its work.
If you’re in your 30s, here’s what should be on your radar:
- Start a SIP into equity mutual funds, even if the amount feels small right now
- Increase your savings rate every time your income grows, not just your spending
- Avoid parking long-term money in low-return instruments like savings accounts or short-term FDs
- Build a separate emergency fund so you’re never forced to break your retirement savings
If your risk profile allows, this is the decade to give equity a large share of your retirement money, since you have time to ride out short-term ups and downs. I’ve written more about why this specific decade matters so much in Newlyweds can double their retirement corpus by starting early, which walks through the numbers in more detail.
In Your 40s: Course-Correct, Increase Contributions, Get Serious
Your 40s are usually your highest-earning years, but they also come with competing financial goals – a child’s education, a home loan, aging parents. This is exactly why retirement financial planning in this decade needs to be deliberate rather than assumed.
The good news is that you likely have 15 to 20 years left before retirement, which is still enough time for a meaningful correction if you started late or under-saved in your 30s. The bad news is that this window closes fast, and every year of delay from here has a much bigger impact than it did a decade ago.
If you’re in your 40s, this is where I’d focus your attention:
- Run an actual calculation of your target retirement corpus instead of guessing
- Increase your SIP amount meaningfully, not just by a token percentage
- Review whether your asset allocation is still too conservative or too aggressive
- Make sure a major expense, like your child’s education, doesn’t quietly eat into retirement savings
One habit that quietly damages this decade’s progress is lifestyle creep – the tendency to spend more simply because you’re earning more. I explored this in detail in Lifestyle Creep Can Halve Your Retirement Corpus, and it’s a pattern worth checking yourself against, especially in your peak earning years.
In Your 50s: Protect What You’ve Built and Sprint to the Finish
By your 50s, the conversation shifts from accumulation to protection. You likely have far less time to recover from a major mistake, which means both your investment choices and your risk tolerance need to evolve.
This doesn’t mean abandoning equity altogether – inflation doesn’t stop just because you’re closer to retirement. But it does mean actively rebalancing your portfolio so a market downturn in your last working years doesn’t derail decades of disciplined saving.
If you’re in your 50s, here’s where I’d direct your energy:
- Get a precise, updated number for your target retirement corpus, not an old estimate
- Gradually shift a portion of your portfolio toward more stable, lower-volatility assets
- Ensure your health insurance cover is adequate, since medical costs are the biggest wildcard in retirement
- Have a clear withdrawal strategy ready, rather than figuring it out after you’ve already stopped working
This is also the decade where a second opinion becomes especially valuable. The margin for error is thin, and someone reviewing your plan with you can spot gaps you might miss. The margin for error is simply too thin to manage this alone, and a second set of eyes can catch gaps you won’t see on your own.
How Much Retirement Corpus Do You Actually Need?
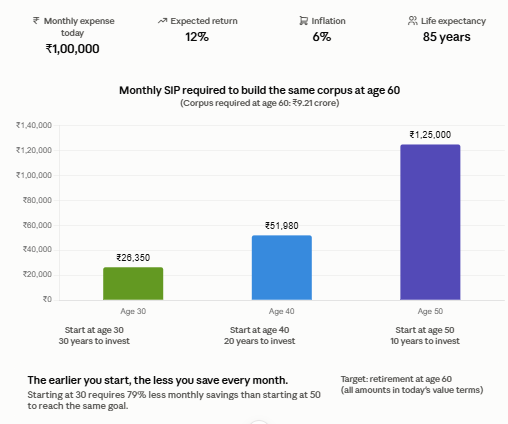
There is no single retirement corpus number that works for everyone. It depends on your expenses, inflation, retirement age, expected returns and how long the corpus needs to last.
For illustration, if you are 30 today, spend ₹1 lakh a month, plan to retire at 60, and assume 6% annual inflation, your monthly expenses could rise to about ₹5.74 lakh by retirement. If your retirement portfolio earns an assumed 12% annually and needs to support you from age 60 to 85, you would need a corpus of approximately ₹9.21 crore at age 60. If the portfolio earns 8% instead, the corpus needed rises to about ₹13.8 crore – which is why the return you assume matters.
Returns are not guaranteed. This is an illustration based on these assumptions, not a universal target. Your actual requirement will vary based on your personal circumstances and investment returns.
For more retirement scenarios, including early-retirement timelines, see How much is enough for early retirement?.
Retirement Investment Strategy: How Your Approach Should Shift With Age
Your retirement investment strategy should never be static. What makes sense at 32 is often the wrong approach at 52, and one of the most common errors I see is investors keeping the same portfolio for 20-plus years without ever revisiting it.
In broad terms, your 30s call for an aggressive, equity-heavy approach since you have time to absorb volatility. Your 40s call for a more balanced mix, still growth-oriented but to reduce risk as your time horizon shortens. Your 50s call for a deliberate shift toward capital protection, without giving up on growth altogether, since your money still needs to outpace inflation for another 25-plus years after you retire.
This is precisely the kind of asset allocation work that benefits from professional guidance, since getting it wrong in either direction – too conservative too early, or too aggressive too late – can be costly. You can read more about how we approach this on our Retirement Planning page.
Retirement Planning for Salaried People in India
If you’re salaried, you already have a head start most people underestimate – instruments like EPF and, in some cases, NPS are quietly building a base for you every single month. The mistake is assuming these alone are enough.
For most salaried professionals I work with, EPF and NPS cover a meaningful portion of the retirement corpus, but rarely the whole target, especially with today’s inflation and rising post-retirement life expectancy.
EPF offers a long-term, low-risk savings base with a rate of interest declared each year by the EPFO. Because its returns are modest, most people need growth-orientated investments such as equity mutual funds alongside it. NPS, regulated by the Pension Fund Regulatory and Development Authority, can add to this base but has its own rules on withdrawals and annuity purchases at retirement.
The practical takeaway: treat your EPF and NPS contributions as your retirement plan’s foundation, and build your SIPs and other investments on top of that foundation, rather than assuming the foundation alone will get you there.
A Word on Getting This Right
Retirement is the one financial goal you don’t get a second chance on. If you fall short on a shorter-term goal, like your child’s education, you have options – a loan, selling an asset, adjusting the plan. If you fall short on retirement, those options largely disappear, because by then, your ability to earn has typically ended too.
That’s exactly why I keep coming back to the same advice regardless of which decade a client is in: know your number, build a plan specific to your age and situation, and revisit it regularly rather than setting it once and forgetting it. If you’d like help putting real numbers behind your own plan, we’re happy to go through the numbers with you at no charge – we’re paid by fund houses, not by clients, as explained on our About Us page.
Rohin Pagdiwala
Founder – Pagdiwala Investments, Mumbai
AMFI-registered Mutual Fund Distributor ARN 186203
APMI-registered PMS Distributor APRN 00370
Tel: 9004231834
Mutual Fund investments are subject to market risks; read all scheme-related documents carefully. Past performance may or may not be sustained in the future and is not a guarantee of future returns.
PMS is available only to eligible investors (minimum investment ₹50 lakh, except for accredited investors) and carries higher risk. This content is for general information only and is not investment advice.
Pagdiwala Investments is an AMFI-registered Mutual Fund Distributor (ARN 186203) and an APMI-registered PMS Distributor (APRN 00370). Pagdiwala Investments is not registered with SEBI as an Investment Adviser. See the About Us page, the registrations and certifications (you can verify them on AMFI’s website) and the full range of Products & Solutions.
This article is intended for general information and investor education only. It does not constitute investment, tax or legal advice, or a recommendation to buy, sell or hold any particular security, mutual fund scheme or other investment product. Investment decisions should take into account an investor’s financial circumstances, objectives, investment horizon and risk tolerance. Readers should consult appropriately qualified professionals where necessary.
Data is as of dates shown.