You can own ten investments and still have no financial plan. Many people log in, see a healthy total and assume everything is on track. The statement shows what you own. It doesn’t show whether it adds up to what you need.
That gap is why the importance of financial planning goes beyond saving more. Financial planning helps you define your goals, estimate when you’ll need the money, and consider the level of investment risk appropriate to your circumstances. Here’s what a plan reveals that a portfolio statement can’t.
Why Is Financial Planning Important?
Financial planning matters because it ties your money to specific goals, dates and risk limits. Without it, investments pile up one decision at a time and nobody checks whether they work together. A plan turns scattered products into one picture. You can see whether you’re on track for retirement, a child’s education or a home, and what to change if you aren’t.
A plan does not guarantee returns. Markets can fall and equity funds can lose value. What it gives you is clarity and a method for making decisions, instead of reacting to the latest tip or headline. If you’re starting from scratch, our complete guide to financial planning in India covers how to build a plan step by step.
What Your Portfolio Statement Can’t Tell You
A statement reports value, units and recent returns. It stays silent on the questions that matter more. A balance can look comfortable and still fall short of a goal fifteen years away. These are the questions a plan answers:
- Is this corpus enough for my retirement date and lifestyle?
- Do several of my funds hold the same stocks?
- Does the investment risk match the year I need that money?
- Is my health and life cover enough for my family?
- Could I handle a job loss without breaking long-term investments?
These gaps rarely announce themselves. They usually surface only when someone maps your whole portfolio against your goals.
Benefits of Financial Planning You Can Actually Measure
The benefits of financial planning show up as specific numbers and decisions, not vague comfort. You know your target corpus, the monthly amount that works towards it, and the date you’ll next review it.
- Goal clarity: every investment is tagged to a purpose and a date.
- A cleaner portfolio: duplicate or idle holdings become visible and can be rationalised.
- Risk matched to the goal: investments for near-term needs can focus on liquidity and lower volatility, while long-term investments may include equity exposure depending on the investor’s risk tolerance and financial circumstances.
- Protection checked first: your emergency fund and insurance are reviewed before growth investments.
- Fewer rash decisions: a written plan gives you something to check before you act.
Financial Planning for Long-Term Goals: Why Inflation Changes the Math
Long-term goals are where planning pays off most, because small assumptions compound over decades. Inflation is the biggest one. Inflation can increase the cost of long-term goals over time. India’s retail inflation figures provide a broad indication of price changes across the economy, but your own expenses, such as school fees, healthcare and lifestyle costs, may rise faster or slower. When planning for retirement or education, consider how changing costs could affect the amount you need in the future.
As an illustration only, at an assumed 5% annual inflation, ₹1 lakh of monthly spending today would grow to roughly ₹2.65 lakh in 20 years. A retirement or education target built on today’s prices would fall well short. Our guides on retirement planning by age and rising education costs show how to build this into your numbers. Inflation figures are assumptions, not forecasts.
Why Financial Planning Helps When Markets Turn Rough
Markets fall, and no plan can stop that. A plan does change how you respond. When every investment has a goal and a date, a dip in a ten-year equity holding looks very different from a dip in money you need next year. That context makes it easier to stay invested instead of acting on fear.
Market downturns can prompt some investors to stop their SIPs or make decisions based on short-term market movements. Reviewing investments against their goals, time horizons and risk tolerance can help investors make more considered decisions. Continuing an SIP should still depend on their financial circumstances and ability to bear risk. A plan also shapes how you spread money across equity, debt and other assets, a theme we explored in building an all-weather investment portfolio. Equity investments can lose value, so the aim is to match risk to the goal rather than assume that risk can be avoided altogether.
How Often Should You Review Your Financial Plan?
Review your plan at least once a year, and again whenever life changes. A new job, marriage, a child, a home loan, an inheritance or a shift in your retirement date can all change what your money needs to do. Reviews also catch quiet drift, such as an equity share that has grown too large, new SIPs never linked to a goal, or outdated nominee details.
Treat each review as a chance to update your family’s access to your finances too. Our What My Family Should Know checklist is a simple place to start. For tax and estate questions, speak to a qualified tax professional or lawyer.
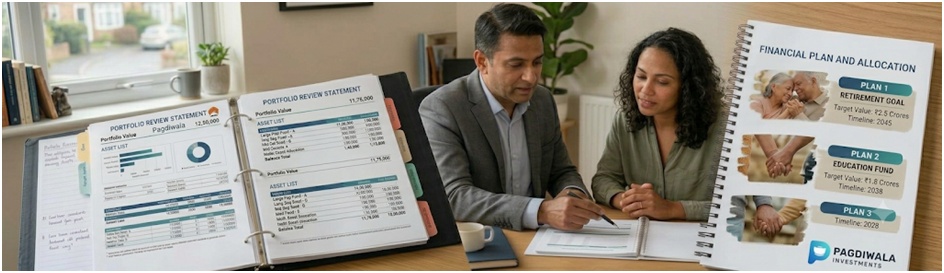
What a Portfolio Review at Pagdiwala Investments Looks Like
Rohin Pagdiwala works with every client personally, and a first conversation starts with your existing statements, not a product pitch. The process is simple:
- Understand your situation: your goals, dates, family and risk comfort.
- Map what you already own: mutual funds, fixed income, insurance and other holdings.
- Review against Goals: Review your existing investments in the context of your stated goals, investment time horizons and risk tolerance, and identify areas that may warrant further consideration.
- Discuss suitable options: like mutual funds where appropriate, within the scope of our registrations and distribution arrangements.
- Review regularly: with real-time portfolio access on app and web, including for NRI clients overseas.
Frequently Asked Questions
Why is financial planning important for salaried professionals?
Salaried income is steady, but goals like retirement and education are large and far away. A plan shows whether your savings, EPF and investments together are enough, and what needs to change.
What are the benefits of financial planning?
You get clear goals, a portfolio matched to them, checked insurance and emergency cover, and a method for staying calm when markets fall.
I already invest through SIPs. Do I still need a plan?
Yes. A SIP is a way of investing, not a plan. A plan checks whether those SIPs match your goals, timelines and risk level.
How is financial planning different from investing?
Investing is choosing where money goes. Planning decides how much, for what, by when and at what risk.
How often should I review my plan?
At least once a year, and after major life events such as a job change, marriage, a child or a home purchase.
Start With a Clear Picture of Where You Stand
A portfolio statement tells you what you own. A plan tells you whether it’s enough, and what to do next. Reviewing your investments in the context of your financial goals can help you understand whether your current arrangements are aligned with your needs and time horizons.
If you have been investing for a while but have never reviewed the overall picture, a portfolio review is a sensible first step.
Request a call back to discuss your existing investments and the distribution services offered by Pagdiwala Investments.
Rohin Pagdiwala
Founder – Pagdiwala Investments, Mumbai
AMFI-registered Mutual Fund Distributor ARN 186203
APMI-registered PMS Distributor APRN 00370
Tel: 9004231834
Mutual Fund investments are subject to market risks, read all scheme related documents carefully. Past performance may or may not be sustained in the future and is not a guarantee of future returns.
Pagdiwala Investments is an AMFI-registered Mutual Fund Distributor (ARN 186203) and an APMI-registered PMS Distributor (APRN 00370). Pagdiwala Investments is not registered with SEBI as an Investment Adviser. See the About Us page, the registrations and certifications (you can verify them on AMFI’s website) and the full range of Products & Solutions.
This article is intended for general information and investor education only. It does not constitute investment, tax or legal advice, or a recommendation to buy, sell or hold any particular security, mutual fund scheme or other investment product. Investment decisions should take into account an investor’s financial circumstances, objectives, investment horizon and risk tolerance. Readers should consult appropriately qualified professionals where necessary.