Most people in India start investing before they start planning. They buy a mutual fund because a friend recommended it, or a policy because an agent called. That’s not financial planning – that’s guesswork with your money.
Financial planning in India means matching every rupee you save to a specific goal, a timeline, and a risk level. Done right, it helps you work towards a retirement corpus, a child’s education fund, and a safety net, all at once. Here’s how to actually build one.
What Financial Planning Really Means
Financial planning is the process of figuring out where your money should go, and why, before you invest a single rupee. It covers savings, investment planning, insurance, taxes, and retirement in one connected picture.
Without it, people end up with a random mix of fixed deposits, one ULIP their uncle sold them, and a couple of mutual funds picked off a YouTube video. None of it is working toward anything specific. A proper plan fixes that by tying each investment to a goal – a house down payment, a child’s college fees, or retirement 25 years out.
If you want a structured starting point, Pagdiwala Investments’ Products & Solutions page breaks down which instruments suit which kind of goal.
Set Goals Before You Set Up a SIP
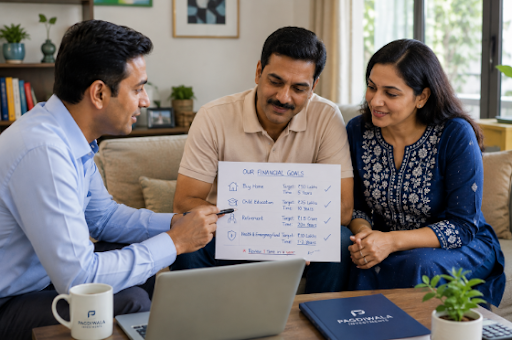
Every financial plan should start with three questions: what are you saving for, how much will it cost, and when do you need the money? Skipping this step is one of the most common reasons plans fall short.
Short-term goals—a car, a wedding, or a vacation—need safer, more liquid options. Long-term goals—retirement, a child’s higher education—can usually take more equity exposure, because a longer horizon gives investments more time to recover from market falls. Equity investments can still lose value over any period.
Write your goals down with real numbers and real dates. “Save for retirement” is a wish. “Build a ₹5 crore corpus by age 58” is a plan you can actually build a portfolio around.
Build an Emergency Fund First
Before any investment planning begins, set aside three to six months of expenses in a savings account, fixed deposit or liquid fund. Liquid funds carry low, but not zero, risk. This single step protects every other financial goal you have.
Without an emergency fund, a job loss or medical bill forces you to break a long-term investment early – often at a loss, and always at the cost of compounding you can’t get back. Keep this money boring, accessible, and separate from your growth investments.
Where Should Your Money Actually Go?
This is where investment planning and mutual fund investment come in. Indian investors today have far more choices than the fixed deposits and gold that dominated their parents’ portfolios.
A sensible starting mix usually includes:
- Equity mutual funds for long-term goals more than 5–7 years away, where growth matters more than stability.
- Debt mutual funds and bonds to cushion volatility and fund medium-term goals.
- PMS (minimum investment ₹50 lakh) or AIFs (generally minimum ₹1 crore) for larger portfolios and investors who can accept the higher risk of more concentrated strategies.
- Term and health insurance – not as an investment, but as protection so a medical emergency never derails your plan.
Mutual funds, in particular, work well for most Indian investors because SIPs enforce discipline and rupee-cost averaging without requiring you to time the market. Remember, SIPs do not guarantee returns or protect against losses in a falling market. According to the Securities and Exchange Board of India, mutual fund distributors are required under the AMFI Code of Conduct to recommend schemes that suit the investor’s financial status, experience and objectives, and SEBI-registered investment advisers have a similar duty. That is why it is worth working with a registered intermediary rather than acting on tips.
Retirement Planning Can’t Wait for “Later”
Retirement planning is the one goal every financial plan must include, yet it’s usually the one people push furthest down the list. Healthcare costs, no pension safety net for most private-sector employees, and rising life expectancy make this riskier to delay in India than almost anywhere else.
The earlier you start, the less you need to save each month, because compounding does most of the work. A 30-year-old needs a fraction of what a 45-year-old needs to save monthly for the same retirement corpus.
Pagdiwala Investments’ Retirement page walks through how to calculate your target corpus based on your current lifestyle and expected retirement age.
Reviewing Your Plan As Your Money Grows
Once your portfolio grows beyond the basics, financial planning shifts into wealth management — actively balancing equity, debt, and alternate investments as your income, goals, and risk appetite change over time.
A plan is not a one-time task. As your income, goals and risk appetite change, your mix of equity, debt and other investments may need to change too. Review it at least once a year as each goal gets closer. For tax and estate matters, consult a qualified tax professional or lawyer.
Common Financial Planning Mistakes to Avoid
A few mistakes show up again and again in Indian households, regardless of income level.
- Stopping SIPs during a market downturn instead of continuing through it
- Buying insurance as an investment product instead of pure protection
- Ignoring inflation when calculating a retirement number
- Holding too much idle cash instead of putting it to work
- Never reviewing the portfolio after the initial investment
Each of these is fixable with a plan and a periodic review—which is where a regular review helps most.
Choosing Who To Work With
In India, two kinds of registered professionals help with investments. SEBI-registered Investment Advisers charge you a fee for advice and do not earn commission. AMFI-registered Mutual Fund Distributors help you choose and invest in schemes and are paid commission by the fund house. They study your full financial history, understand your goals across life stages, and help you avoid emotional decisions during volatile markets. Whoever you choose, check their registration on the SEBI or AMFI website and ask how they are paid.
Look for someone with a long track record across multiple market cycles, a wide product range spanning mutual funds, PMS, AIFs, and insurance, and a transparent fee or commission structure. The National Centre for Financial Education publishes independent guidance on investing, which is worth reading.
Pagdiwala Investments is an AMFI-registered Mutual Fund Distributor (ARN-186203) and APMI-registered PMS Distributor (APRN-00370).
Frequently Asked Questions
What is the first step in financial planning? Setting clear, dated goals before choosing an investment. Decide what you’re saving for and by when before picking any product.
How much should I invest every month? A common starting point is 20% of take-home income, split across an emergency fund, retirement savings, and other goals based on their timelines. However, this percentage should increase rapidly as income increases.
Are mutual funds suitable for beginners in India? Mutual funds are market-linked; returns are not guaranteed, and you can lose money. Each scheme shows a riskometer that rates its risk level. For many new investors, a diversified scheme that matches their risk profile and goal is a reasonable way to start.
When should I start retirement planning? As early as your first paycheck. Starting in your 20s versus your 40s can cut your required monthly savings dramatically due to compounding.
Do I need professional help, or can I invest on my own? You can invest on your own through Direct Plans, which have lower expense ratios because no distributor commission is paid. This works if you have the time and knowledge to choose schemes, track them and rebalance regularly. A distributor helps with scheme selection, paperwork and reviews, and is paid a commission which is included in the Regular Plan’s expense ratio.
What’s the difference between financial planning and wealth management? Financial planning covers goal-setting and the initial investment mix. Wealth management is the ongoing process of adjusting that portfolio at least once a year, and whenever your income, family situation or goals change.”
Start Your Financial Plan Today
Financial planning in India isn’t about picking the perfect fund – it’s about building a system where every investment has a job to do. Set your goals, protect yourself with an emergency fund and insurance, and revisit the plan every year.
If you’d rather not build this alone, Pagdiwala Investments’ Blog has more in-depth guides on retirement, mutual funds, and wealth management, or you can reach out directly for a personalised discussion.
Rohin Pagdiwala
Founder – Pagdiwala Investments, Mumbai
AMFI-registered Mutual Fund Distributor ARN 186203
APMI-registered PMS Distributor APRN 00370
Tel: 9004231834
Mutual Fund investments are subject to market risks; read all scheme-related documents carefully. Past performance may or may not be sustained in the future and is not a guarantee of future returns.
Pagdiwala Investments is an AMFI-registered Mutual Fund Distributor (ARN 186203) and an APMI-registered PMS Distributor (APRN 00370). Pagdiwala Investments is not registered with SEBI as an Investment Adviser. See the About Us page, the registrations and certifications (you can verify them on AMFI’s website) and the full range of Products & Solutions.
This article is intended for general information and investor education only. It does not constitute investment, tax or legal advice, or a recommendation to buy, sell or hold any particular security, mutual fund scheme or other investment product. Investment decisions should take into account an investor’s financial circumstances, objectives, investment horizon and risk tolerance. Readers should consult appropriately qualified professionals where necessary.
Data is as of dates shown.