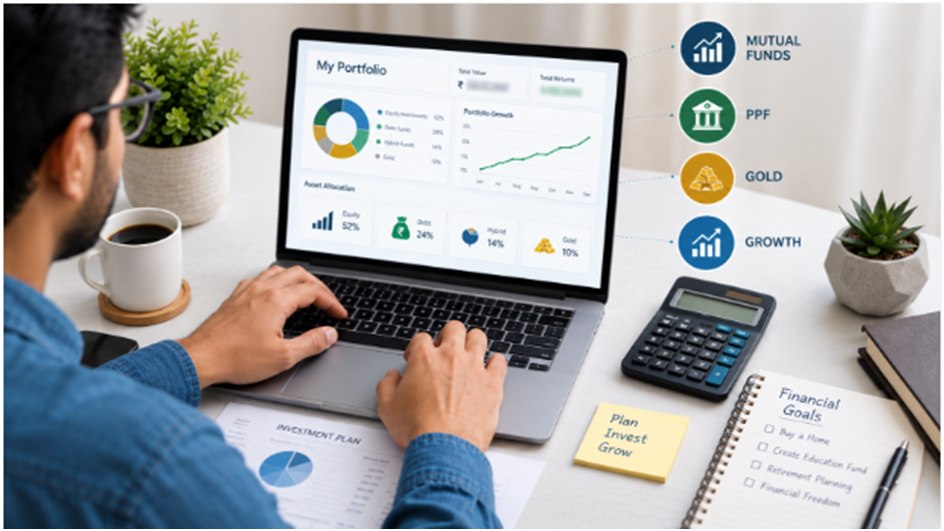
Most people ask “what’s the best investment plan?” the same way they’d ask for the best phone – expecting one answer that works for everyone. It doesn’t exist. The best investment plan is the one that matches your goal, your time horizon, and how much risk you can actually sleep through.
This guide breaks down how to think about investment options in India today, what the current numbers actually look like, and how to build a plan instead of just picking a product.
What Makes an Investment Plan “the Best” for You?
There’s no single best investment plan in India – there’s only the best plan for your specific goal, timeline, and risk appetite. A plan built for a 3-year car purchase looks nothing like one built for a 25-year retirement corpus.
The right plan balances four things: how soon you need the money, how much volatility you can handle without panicking, what is the growth rate you need, and how the returns are taxed. Get any one of these wrong, and even a “good” fund or scheme can leave you short of your target.
This is exactly why a generic ‘best investment options in India’ listicle can be misleading. A fund that suits a 28-year-old with a 20-year horizon can be a poor fit for someone retiring in five years.
Know Your Goal and Time Horizon First
Before comparing products, write down what you’re saving for, how much it will cost in today’s rupees, and when you’ll need it. This single step decides almost everything else about your plan.
Short-term goals of one to three years – a wedding, a down payment, a planned upgrade – belong in low-volatility instruments like debt funds, arbitrage funds, etc. where stability matters more than growth. Medium-term goals of three to seven years can take on a mix of debt and equity. Here’s where balanced advantage or other hybrid funds may fit in. Long-term goals of seven years or more, like retirement or a child’s higher education, can absorb more equity exposure because time smooths out short-term swings.
If you haven’t mapped your goals yet, Pagdiwala Investments’ Products & Solutions page is a useful starting point – it lists various instruments available for investment so that you can identify what might best suit your goals.
Investment Options in India: Where Things Stand in 2026
For Jul–Sep 2026, government-backed small savings scheme rates remain unchanged for the ninth quarter running. The Public Provident Fund (PPF) offers a 7.1% tax-free return under the EEE regime. The Sukanya Samridhi Yojana and the Senior Citizen Savings Scheme both offer 8.2%, while the National Savings certificate offers 7.7%. You can check the live rate card on the National Savings Institute’s official site before investing.
Beyond small savings, most well-planned portfolios in India combine a few of these. Keep in mind that these are not guaranteed return products, and some of them carry market risks.
- Equity mutual funds – for long-term wealth creation through SIPs, which spread investments over time but do not guarantee returns or protect against market losses.
- Debt & hybrid mutual funds – for medium-term goals and to cushion overall portfolio volatility.
- PPF, SSY, or NSC – for guaranteed, tax-efficient long-term savings with government backing.
- PMS or AIFs – for larger, more concentrated portfolios (minimum investment of ₹50 lakh for PMS and ₹1 crore for AIFs) once your corpus and risk appetite justify such strategies.
- Term and health insurance – not an investment, but the protection that keeps a medical emergency from derailing everything else.
None of these is inherently ‘better’. The right combination depends entirely on the goal you’re funding.
Investing for Long-Term Goals
For anything seven years or further away – retirement being the most common example – equity-orientated mutual funds and, for larger portfolios, PMS or AIFs, tend to do the most work provided your risk profile justifies the volatility of such products. Over long periods, equity has historically outpaced inflation more consistently than fixed-income instruments, though returns are never guaranteed and short-term volatility is part of the deal.
For a deeper breakdown of how to plan by age and life stage, see Pagdiwala Investments’ guide to retirement planning by age and explore the retirement planning page for more information on preparing for retirement.
Tax-Saving Investment Options You Shouldn’t Overlook
Tax year 2026-27 falls under the Income-tax Act, 2025, which renumbers sections (80C → 123, 80CCD → 124, 87A → 156).
Because tax rules change with almost every Budget, always verify the current provisions on the Income Tax Department’s official portal before finalising which regime and products suit you. Please also speak with a registered tax consultant or chartered accountant before making any investments in these products.
Common Mistakes That Quietly Ruin a Good Plan
Even a well-chosen investment plan can underperform if a few habits go unchecked. These show up across income levels and age groups in India:
- Stopping SIPs during market downturns instead of continuing through them
- Chasing last year’s top-performing fund instead of one which has a more consistent long-term track record
- Skipping creation of an emergency fund before starting long-term investments
- Ignoring how a product is taxed before comparing its headline return
- Never reviewing the portfolio after the first investment is made
Continuing SIPs during volatile markets, in particular, is one of the most common and costly mistakes investors make. Pagdiwala Investments’ article on why stopping SIPs during downturns is a mistake walks through why staying invested usually beats trying to time an exit.
How a Mutual Fund Distributor Can Help You Choose
A good distributor doesn’t just sell a fund – they understand your goals and risk tolerance before suggesting anything. That process matters more than the specific product, because the same fund can be right for one investor and wrong for another with a different timeline.
Look for someone with a track record across multiple market cycles, a product range that spans mutual funds, fixed income, and alternatives rather than just one category, and full transparency on how they’re compensated. Under the SEBI-prescribed Code of Conduct, AMFI-registered mutual fund distributors must consider an investor’s needs and risk profile before recommending a scheme – one of many reasons why working with a SEBI-registered Investment Adviser or an AMFI-registered Mutual Fund Distributor is safer than following unsolicited tips.
If you’re choosing a mutual fund distributor in Mumbai, Pagdiwala Investments’ About Us page outlines the credentials and experience worth checking, and the firm’s registrations and certifications are listed publicly for verification.
Frequently Asked Questions
What is the best investment plan for beginners in India?
The best plan is always one that is personalized based on the risk profile and return expectations of the investor. One should consult a SEBI-registered Investment Adviser or an AMFI-registered Mutual Fund distributor before investing.
What is the best investment plan for long-term wealth creation?
Assuming that the financial goal is at least 7 years away and the investor has some prior experience in investing in equity markets and can stomach market volatility, equity mutual funds through disciplined SIPs is generally a good option that could beat inflation, provided you can handle the volatility. However once again, it is advisable to consult an AMFI-registered Mutual Fund distributor or a SEBI-registered Investment Adviser before making any investment decisions.
Are mutual funds safer than fixed deposits?
No – mutual funds are market-linked and carry equity risk that fixed deposits don’t. They aren’t “safer,” but over long horizons they’ve historically offered better inflation-adjusted returns for investors who can tolerate short-term ups and downs. However, there is no guarantee of receiving similar returns in the future.
Do I need professional help to build an investment plan?
Not strictly, but most investors benefit from professional guidance, especially once goals multiply and a portfolio spans several product categories. A SEBI-Registered Investment Adviser charges you a fee for advice; an AMFI-registered Mutual Fund distributor such as Pagdiwala Investments is paid commission by Asset Management Companies and does not charge you a fee.
Building Your Plan Starts With One Decision
The best investment plan isn’t a product you buy once – it’s a system that matches every rupee to a goal, a timeline, and a risk level and gets reviewed as your life changes. Start with your investment goals, protect yourself with an emergency fund, and only then pick the other mutual fund, PMS or AIF schemes.
Rohin Pagdiwala
Founder – Pagdiwala Investments, Mumbai
Tel: 9004231834
AMFI Registered Mutual Fund & SIF Distributor – ARN-186203
APMI Registered PMS Distributor – APRN 00370
Mutual fund investments are subject to market risks; read all scheme-related documents carefully before investing. Past performance may or may not be sustained in the future.
Pagdiwala Investments is not registered with SEBI as an Investment Adviser. This article is for general information only and should not be construed as investment advice.
PPF, SSY, NSC, SCSS, fixed deposits and insurance are not mutual fund products. Please consult a registered SEBI Investment Adviser before investing in them.